Buoyed by fast-growing economies, young populations, and wider mobile phone use, Southeast Asian startups drew investors in the early 2020s. But enthusiasm cooled after the pandemic as capital costs rose, the artificial intelligence boom drew investment toward China and the US, and high-profile scandals cast a shadow over the sector, particularly in Indonesia.
Equity funding has shown signs of recovery in 2026, reaching its highest level in four years, albeit largely driven by a two-tranche round for DayOne Data Centers, according to DealStreetAsia. However, this year there have been no new unicorns—companies with a USD 1 billion valuation—for the first time since 2018.
While investors, founders and others in the region’s ecosystem welcomed the uptick, many said deeper structural factors had constrained the region’s growth and act as a brake on future potential. With the exception of Singapore, four themes stand out: a lack of openness to foreign entrepreneurs, unpredictable legal regimes, shallow depth of capital, and difficulty in expanding abroad.
“These companies that we are backing in Southeast Asia only function in Southeast Asia. In fact, they only function in the key economies of Southeast Asia,” James Tan, managing partner at Quest Ventures, a leading Southeast Asian venture capital firm, told Nikkei Asia. “Whereas if you are in Silicon Valley, you are building for the world.”
Even at its height in 2021, the boom was narrow. Nearly 60% of the region’s unicorns listed by DealStreetAsia are incorporated in Singapore and 18% are in Indonesia.
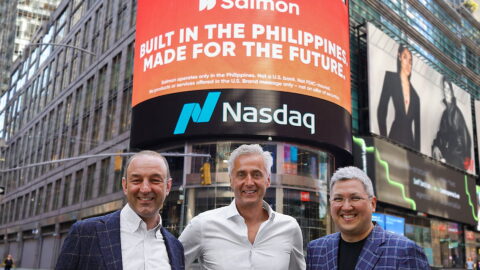
Furthermore, even the top performers look underweight by global standards. Grab, the region’s top ride-hailing and delivery app based in Singapore, listed on the Nasdaq in New York in 2021 via the world’s largest merger through a special purpose acquisition company valued at USD 39.6 billion. Today its market cap sits around USD 12.25 billion. Uber, in contrast, has a valuation of nearly USD 150 billion.
Over 80% of all founders of unicorn companies in Singapore had foreign origins, according to research by Nikkei Asia based on DealStreetAsia’s list of unicorns. Of these, 15.5% were from other ASEAN member states.
Foreign-origin unicorn founders are scarce elsewhere in the region, apart from Indonesia. Singapore’s large foreign population helps explain the difference, but other countries are also home to affluent, educated foreigners.
Outside Singapore, a divide can exist between foreign and domestic startup ecosystems.
“Thai startups, aside from those in the high profile accelerators, we rarely have direct access to them,” said Mike Miguel, general partner at ASEAN-focused venture capital fund 90 Proof Capital. “Those we do get access to in the wild, their cap table has already been gobbled up by a school or government-funded incubator.”
A company’s cap (capitalization) table is its breakdown of stock ownership, and how much is available to pre-IPO investors.
Trung Hoang, a partner at VinaCapital Ventures, a Vietnam-based venture capital investment fund, told Nikkei Asia that the country “is more open than many people think.”
But he added that Vietnam’s ecosystem has been built around local founders, domestic markets, and local execution capability.
“As a result, foreign founders often find that relationships, local market knowledge and trusted local partners are particularly important,” he said.
For Indonesia the scope of opportunities as the region’s largest economy might be behind its ability to attract foreign founders.
“Indonesia’s large economy, a 280 million population, and admittedly many, many problems which meant many, many opportunities attracts many foreigners to try to tackle these problems,” said Eddi Danusaputro, chair of the Indonesian Venture Capital Association for Startups.
Onerous and unpredictable bureaucracy also looms large.
“Thailand can be a great place to build a business, it’s just that its complexity makes being prepared and having experienced local guidance less of an option and more of a necessity,” said Cleveland Cliff English III, whose Bangkok firms, Br’er Rabbit Legal, and Br’er Rabbit Advisory, provide legal and corporate advice.
“I set up companies in Iraq and Afghanistan during the wars. It was actually easier,” he said, adding that if Thailand “wasn’t so amazing, and the value for money so great, nobody would want to set up a business here.”
Regulatory issues are particularly burdensome for foreign entrepreneurs in Thailand. Many seek approval from the Board of Investment, which can permit full foreign ownership and offer generous tax incentives for eligible activities. English estimates that the overall process can take up to a year if applicants are not adequately prepared.
The result is that many incorporate in Singapore.
“For companies looking to expand across Asia, having a holding company in Singapore or Hong Kong can make international expansion and fundraising easier,” said Jason Bernard, founder of Jadou Technologies, based in Bangkok, which is seeking to develop drones that remove carbon monoxide from the air.
“These jurisdictions offer corporate structures that are more familiar to international investors, helping reduce investment friction and making future funding rounds easier to navigate.”
The next issue is a relative lack of funding.
Southeast Asia does “have a very vibrant late-stage venture capital fund market or ecosystem,” Tan said. However, Singapore monopolizes this. In the first half of 2026 companies headquartered in the city-state captured nearly 92% of equity funding in the region, according to DealStreetAsia.
Bui Hoai Nam, CEO of UrBox, a digital rewards and employee benefit solution platform in Vietnam, founded his company in 2015. It took three years to secure his first investment round and his last round was in 2021.
Nam believes that fundraising challenges facing startups across the region include a lack of tolerance for serial entrepreneurs with past failures, small players being squeezed out by major corporations’ tech investments, an abundance of tech talent making copycatting any successful model easy, and “problems of founder compliance and integrity” making investors more cautious.
The last point weighs particularly heavily on Indonesia, which has been rocked by several scandals, notably eFishery, an Indonesian unicorn that collapsed amid allegations of extensive misreporting of its financial performance.
“The scandals have clearly affected confidence, particularly when the companies involved were backed by established institutional investors and had been presented as success stories for the region,” Anil Rai, partner at the Singapore-based consulting firm YCP, told Nikkei Asia.
The result is investors in the region have become more cautious. They demand more information, spend more time on due diligence, and put more emphasis on financial controls before investing.
“That creates additional difficulties for genuine businesses,” Rai added.
Outside Singapore, limited funding constrains expansion and can force founders to surrender substantial equity for little capital, leaving less to offer future investors.
“A lot of the college kids I talk to in Thailand or Vietnam have had a substantial part of their cap table hamstrung in exchange for lock, stock and barrel incubation, some office space, and many times a disproportionately low check that many times never even reaches them, long after the news release,” Miguel said.
Similarly, in Vietnam “there is far less growth capital than there are growth-stage companies,” Hoang said. This gives investors pricing power. “That can lead to larger equity concessions than founders might face in deeper markets.”
The bigger problem, people said, is a shortage of exits, which discourages investors and limits capital available for reinvestment.
“The liquidity is not there yet,” said Hoang, whose fund has invested in UrBox. “In our portfolio of the very first fund, we’ve been able to bring one company to IPO back in 2018, but that’s it. All of the other exits have been done either via strategic sales or M&A.”
In Vietnam, IPO rules require a company to have two years of profit and no accumulated losses. This fits badly with the high cash-burn models of many tech startups.
But across the region, countries with more flexible listing requirements also struggle to offer attractive exits. The Indonesia Stock Exchange changed its rules to allow the listing of e-commerce and ride-hailing giant GoTo at a market cap of USD 33 billion in April 2022. After hitting a peak of IDR 442, or about USD 0.03 at the time, its share price is now trading at IDR 23. Other unicorns like Bukalapak have also seen their valuations collapse.
“I hear more and more startups considering regional bourses, including Hong Kong,” Danusaputro said. Singapore is less on the radar for them.
Indeed, even Singapore struggles with exits, Tan observed. The country is Southeast Asia’s Silicon Valley, New York, and Delaware rolled into one—a hub of tech talent, finance and corporate registrations, he said.
“And yet our stock market for technology stocks is non-existent,” he said. “That just boggles the mind.”
Deeper capital pools and analysts accustomed to valuing high-growth tech companies make the Nasdaq and the New York Stock Exchange a mecca for listings, Tan said.
But the supposed greater access to capital a US listing affords can be illusory, as such ASEAN stocks often languish, overlooked by analysts.
“The cons of listing in the US are that nobody there understands what’s happening in the markets that we are in,” Tan said. “Investor understanding of anywhere outside of the US and particularly in Southeast Asia is practically non-existent.”
Some see positive signs, however. Pointing to the recent uptick in activity, Miguel suggests that while “tourist capital” from the era of cheap rates may have gone, a new generation of more patient capital is developing.
Governments and stock exchanges are also trying to capture more benefits from the tech economy.
The Singapore Stock Exchange now allows dual listings on its bourse and the Nasdaq. The Stock Exchange of Thailand has amended its rules to ease listing requirements for “new economy” companies and also allow dual listings. Malaysia’s Bursa hiked profit requirements but eased listing requirements in other ways. And Vietnam’s government is establishing international financial centers to deepen domestic capital pools.
Indonesia might continue to struggle though. The moves by global index provider MSCI to downgrade its stock exchange from emerging market to possibly standalone market status have sucked capital out of the country.
But the final challenge of scaling beyond home markets persists. Expanding into neighboring countries seems logical, given ASEAN’s USD 4.5 trillion combined economy spread across 11 economies. But regulatory, linguistic and cultural differences between countries mean “it’s not easy to scale in all countries at the same time,” said Nam.
This issue of cultural gaps is amplified by the nature of many Southeast Asian startups. Successful ones often rely less on innovation than on copying established business models and then winning domestic markets based on deep local knowledge, argued Tan.
But “deep local understanding also means that you have to be very local,” he said. “And how many markets can you be very local in—in say a short span of ten years?”
This article first appeared on Nikkei Asia. It has been republished here as part of 36Kr’s ongoing partnership with Nikkei.